Your Job Is Your Credit
The concept of “Your Job Is Your Credit” is a financial approach that evaluates a person’s ability to repay loans based on steady employment and income rather than traditional credit scores. This method helps millions, including first-time borrowers, individuals with poor credit, and immigrants without a credit history, by offering quicker loan approvals in places like used car dealerships and rent-to-own stores.
By verifying job stability through recent pay stubs and employment proof, this system provides a fair chance for responsible workers to rebuild credit and access essential goods, making “Your Job Is Your Credit” a valuable alternative in today’s lending world.
| Basics | Summary |
| Concept | Loans based on job, not credit score. |
| Evaluation | Income and job stability checked. |
| Usage | Common in car and rent-to-own stores. |
| Purpose | Helps those with poor or no credit. |
| First-Time Borrowers | Builds credit via employment proof. |
| Poor Credit | Rebuilds credit using steady income. |
| Immigrants | Aids newcomers lacking a credit history. |
| Car Dealers | Approve with pay stubs, no credit check. |
| Furniture Stores | No-credit-needed payment plans offered. |
| Qualification | Requires job proof, ID, and no credit check. |
| Advantages | Easier access to loans and goods. |
| Fast Approval | Quick decisions without credit checks. |
| Flexible Payments | Payments match the income schedule. |
| Disadvantages | Higher interest rates are possible. |
| Limited Access | Available at select retailers only. |
| Advice | Read the terms carefully before signing. |
What Does “Your Job Is Your Credit” Really Mean?
“Your Job Is Your Credit” is a financial approach where lenders evaluate your ability to repay based on your income rather than your credit report. In this model, consistent employment and regular paychecks act as proof of your creditworthiness. It’s commonly used in car dealerships and rent-to-own companies. The goal is to offer opportunities to responsible workers who may have weak, nonexistent, or damaged credit, but still demonstrate financial reliability through employment.
Who Typically Benefits from This Lending Method?
First-Time Borrowers Starting Their Credit Journey
People new to credit, such as young adults or recent graduates, often struggle to qualify for financing. Without a credit history, lenders can’t assess their risk using traditional methods. However, “Your Job Is Your Credit” changes this by allowing these individuals to gain access based on employment alone. It provides them a practical, fair way to begin building a credit profile through timely repayments tied to their earned income.
Individuals with a Poor Credit History
Many people face financial issues that hurt their credit scores—medical bills, job loss, or unexpected expenses. Traditional lenders usually deny their applications. With Your Credit,” lending, your recent income plays a more critical role than past financial mistakes. This approach gives hardworking individuals the opportunity to rebuild financially and responsibly, even if past borrowing didn’t go well. A steady job becomes a second chance toward credit recovery.Newcomers often arrive without an established credit history, making it difficult to secure loans. However, many immigrants quickly find steady jobs and earn a consistent income.
Used Car Dealerships and Buy-Here-Pay-Here Lots
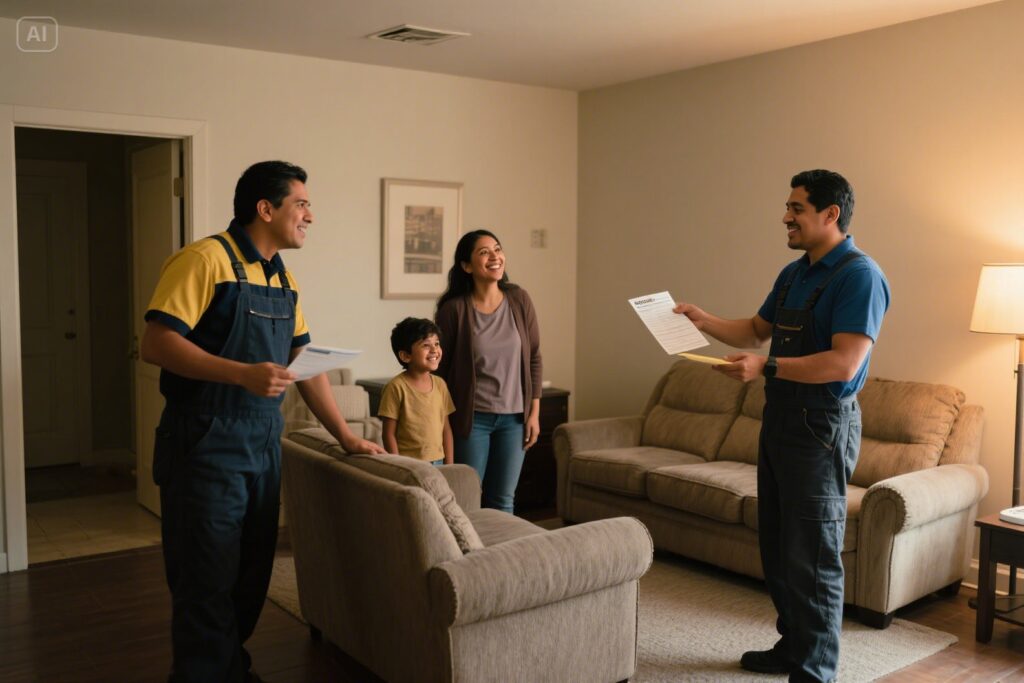
Car dealerships specializing in used vehicles frequently offer “Your Job Is Your Credit” options. Instead of running credit checks, they request recent pay stubs and proof of employment. If the buyer can verify income and employment stability, they’re often approved on the spot. This opens opportunities for buyers with past financial trouble to own a vehicle, which is usually a necessity for commuting to work or supporting a household.
Furniture and Appliance Stores Offering Payment Plans
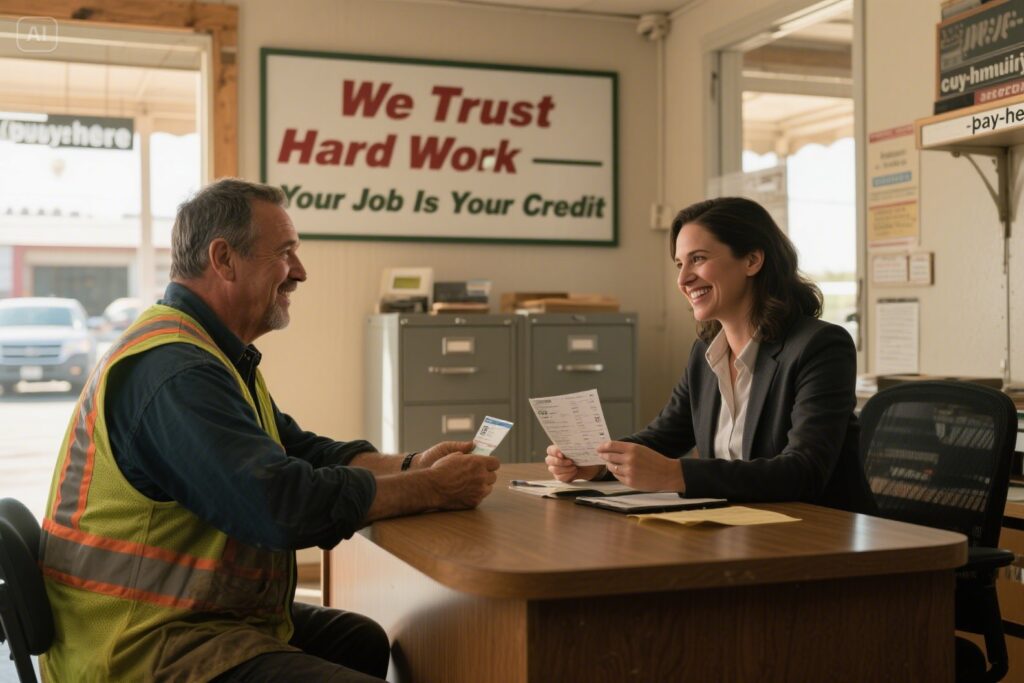
Rent-to-own and local furniture retailers often advertise no-credit-needed deals. Customers only need to show job verification and basic personal documentation. “Your Credit” enables families to furnish their homes with essential items, even when banks say no. This approach builds trust and ensures that hardworking individuals have access to quality furniture and appliances while making regular, affordable payments based on their income schedule and employment situation.
How to Qualify for Financing?
Qualifying under the “Your Job Is Your Credit” model is simple. Most lenders will ask for recent pay stubs, proof of ongoing employment, and a valid photo ID. A utility bill or proof of address may also be required. They usually do not check your credit score. Instead, they assess your ability to make timely payments based solely on how long you’ve been working and your current monthly earnings.
Advantages and Disadvantages
Pros
- “Your Job Is Your Credit” makes financing more accessible for people excluded by traditional systems.
- There’s no credit check, so approval is quicker.
- Borrowers get access to cars, furniture, or electronics when they need them most.
- This model is particularly well-suited for individuals who work steadily and require essential items promptly.
- It allows people to get approved even during financial rebuilding, offering them both flexibility and a fresh financial opportunity.
Cons
- While this method offers wider access, it often comes with drawbacks like higher interest rates or limited inventory.
- Because lenders take more risk by not evaluating credit scores, they offset this by increasing rates.
- Additionally, these programs are typically available only at select dealerships or stores, which means there may be fewer choices.
- Borrowers should read the fine print carefully and make sure they understand repayment terms before agreeing to any contracts.
Conclusion
“Your Job Is Your Credit” offers a practical solution for those with little or poor credit by valuing steady employment and income over traditional credit scores. This approach provides faster approval and access to essential items like cars and furniture. While it may come with higher interest rates, it gives hardworking individuals a second chance to rebuild credit and financial stability, making it an essential alternative in today’s lending landscape.
If you want to read an interesting article about it, explore our “business” category.
FAQs
Used car dealerships and rent-to-own furniture stores often offer loans based on job stability rather than traditional credit scores.
Typically, recent pay stubs, proof of employment, a valid ID, and sometimes proof of address are required to apply without a credit check.
Loans may have higher interest rates and limited availability at select retailers, so it’s essential to review all terms carefully before agreeing.